Introduction
Marriage changes a lot of things, and finances are honestly one of the trickiest to navigate early on — different spending habits, different risk appetites, sometimes even different money philosophies entirely. Good financial planning for couples isn’t about merging everything into one account on day one; it’s about building a shared system that respects both partners’ comfort levels.
Have the Honest Money Conversation First
Quick Answer: Before making any joint financial decisions, newly married couples should openly discuss income, existing debts, spending habits, and financial goals, since unspoken assumptions about money are one of the most common sources of conflict in marriages.
Decide on Joint vs Separate Accounts (Or Both)
There’s no single right answer here, and I’d push back on anyone who insists otherwise. Some couples thrive with fully joint finances, others prefer separate accounts with a shared account just for common expenses. A hybrid approach — individual accounts plus one joint account for rent, groceries, and bills — genuinely works well for a lot of couples starting out.
Review and Consolidate Insurance Coverage
- Check if either partner’s employer health insurance can cover the spouse, potentially saving on a separate policy
- Update or add term insurance nominee details post-marriage
- Consider a family floater health plan if both employer covers are inadequate
Set Joint Financial Goals With Timelines
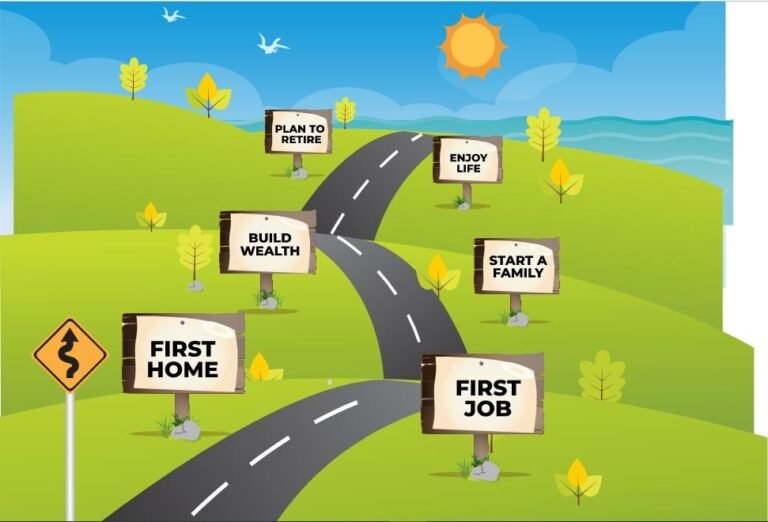
Sit down together and actually list out shared goals — a house down payment, a vacation, starting a family, or clearing existing debt. Assigning rough timelines and required monthly savings to each goal turns vague aspirations into an actual actionable plan. [link to related guide on how much to save monthly for retirement here]
Address Existing Debts Transparently
If one partner enters the marriage with debt — a personal loan, credit card balance, or education loan — this needs an honest conversation about repayment strategy. Whether it stays individually managed or becomes a shared priority is a couple’s choice, but hiding it rarely ends well.
Update Nominee Details Across All Accounts
This gets forgotten surprisingly often. Bank accounts, mutual funds, insurance policies, EPF — all of these need nominee updates post-marriage. It’s a simple administrative task that matters a lot more than its tedium suggests.
Build a Joint Emergency Fund
Combine both partners’ emergency fund efforts into one shared buffer, ideally covering 6 months of combined household expenses. This provides a stronger cushion than two smaller, separate funds that might not fully cover a genuine household emergency.
A Real Scenario
Picture a newly married couple where one partner is naturally a saver and the other more of a spender. Rather than forcing one style onto the other, they set up a joint account for fixed shared expenses (rent, groceries, bills) with an agreed monthly contribution from each, while keeping separate accounts for individual discretionary spending — avoiding the friction of monitoring every personal purchase while still meeting shared goals consistently.
FAQs
Should couples combine all their investments after marriage? Not necessarily — many couples keep individual investment portfolios while jointly tracking overall progress toward shared goals.
How do we handle it if one partner earns significantly more than the other? A common approach is contributing to shared expenses proportionally to income rather than splitting everything equally, though this depends entirely on what feels fair to both partners.
Is it necessary to have a joint bank account after marriage? No, it’s not mandatory — a shared account for common expenses works well for many couples without requiring a fully joint financial setup.
Should we buy a house together immediately after marriage? Not necessarily immediately — build financial stability and a clear repayment plan first before taking on a major joint liability like a home loan.
How often should couples review their joint financial plan? An annual review, or after any major life event like a job change or having a child, helps keep the plan realistic and relevant.
Conclusion
Good financial planning for couples isn’t about forcing identical money habits onto both partners — it’s about transparency, shared goals, and a system that respects individual comfort levels while still building toward common milestones. Start with an honest conversation, update the administrative basics like nominees, and revisit your joint plan at least once a year as life inevitably changes.
Suggested Alt Text: “Newly married couple discussing financial planning together at home”